Let’s be honest: getting your driver’s license is like finally being handed the keys to the candy store—except the candy is adulthood, and the store manager is an insurance agent with a calculator and a grudge. If you’re a new driver under 25, your insurance premium probably costs more per month than your car payments. But don’t panic yet. Some cars are actually cheap to insure, and finding them is like discovering a hidden level of sanity in a video game.
Why Do New Drivers Pay a Fortune?
Insurance companies look at new drivers and see chaos in a baseball cap. Statistically, you are four times more likely to crash than a 40-year-old accountant named Gary. Because of this, insurers slap a “youth tax” on your policy that feels like a ransom demand. But here’s the secret: the car you drive can slash that ransom by hundreds of dollars a year.
Insurers care about two things: how much the car costs to fix, and how likely it is to be stolen. A flashy sports car screams “Please crash me and steal my wheels,” while a sensible hatchback whispers, “I’m doing my taxes and don’t make eye contact.” Guess which one gets the lower premium?
Must Read
Meet the Safety Squad: Cars That Love Your Wallet
1. Honda Civic (The Overachiever)
The Honda Civic is the high school valedictorian of cars: reliable, boring, and somehow everyone’s mom approves. It has excellent safety ratings and cheap replacement parts, which makes insurance companies yawn—and yawning means lower rates. A 2023 study found Civics cost about $1,400 less per year to insure for a teen than the average car. That’s like six months of Netflix, pizza, and gas money combined.
2. Mazda3 (The Fun Dad)
The Mazda3 looks sporty enough to make your friends jealous, but it’s actually a secret adult. Its safety tech—like automatic braking—makes insurers purr with joy. Plus, the Mazda3 is notoriously hard to steal, probably because thieves prefer flashy rides you can pawn. Your premium could be as low as $1,200 a year for a new driver, which is less than what you’d pay for a used bicycle if you counted the repairs.
3. Subaru Outback (The Wilderness Protector)
If your car looks like it could survive a zombie apocalypse, insurers trust you. The Subaru Outback has a five-star crash test rating and standard all-wheel drive, which makes it a favorite for icy roads—and for insurance agents who sleep better at night. One surprising fact: Subarus have the lowest average claim frequency of any brand for young drivers. That means you’re less likely to file a claim, so they reward you with discounts.
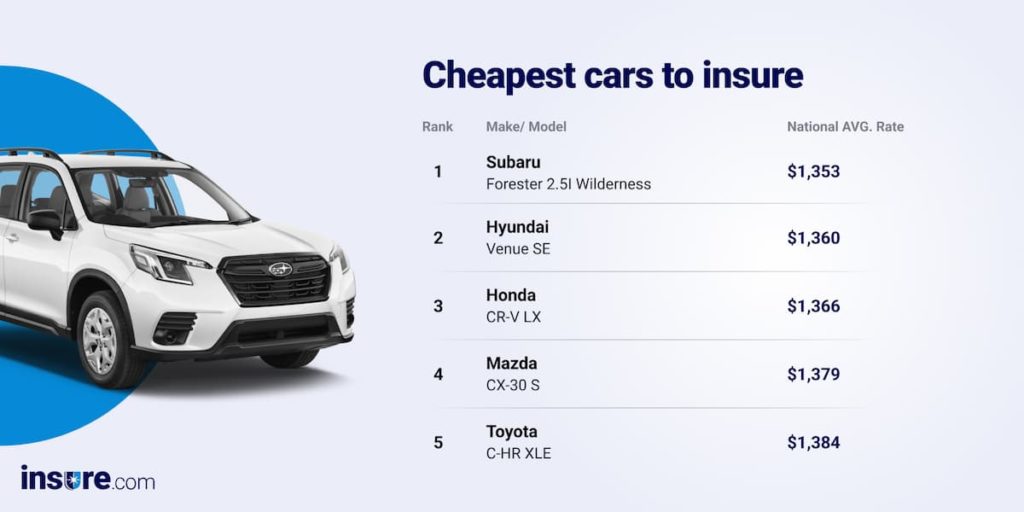 Ranking the most expensive & cheapest cars to insure for 2023
But Wait—There’s a Twist
You might be tempted to buy a 1987 Toyota Corolla for $500 and call it a day. Bad idea. Old cars lack modern safety features like airbags and anti-lock brakes, so your insurance might actually be higher than for a newer model. Insurers don’t care about nostalgia; they care about whether you’ll survive a fender bender. A 2015 Toyota Corolla, however, is the goldilocks zone—cheap to buy, cheap to fix, and illuminatingly safe.
Want to save even more? Consider a 2018 Kia Soul. Yes, it looks like a toaster on wheels, but it’s got a five-star safety rating and laughably cheap insurance. Plus, you can decorate it like a tiny house on wheels—insurance won’t ding you for personality.
The Hyundai Elantra: The Dark Horse
Hyundai has been quietly building cars that insurers love. The 2022 Elantra comes with a built-in camera that tracks your driving—call it your “mom on wheels.” If you drive responsibly, you can get deep discounts of up to 30% through usage-based insurance programs. That’s like getting a cash reward for not being a menace to society. Surprising fact: Hyundais are now stolen more often than some luxury cars, so newer models with immobilizers are your safest bet.
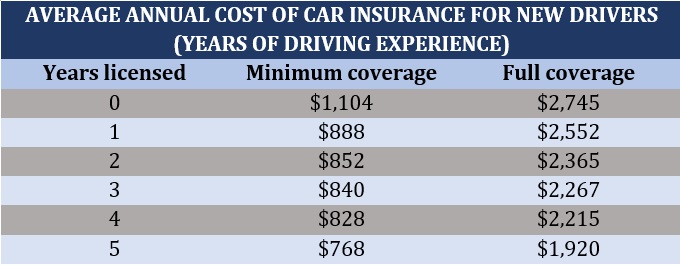 A guide to cheap car insurance for new drivers | Insurance Business
One Final, Embarrassing Truth
No matter what car you pick, your insurance will still be higher than your friend who drives a minivan and listens to talk radio. But here’s a secret trick: add yourself as a secondary driver on your parents’ policy if you live with them. That can drop your rate by 40% or more, because insurers think “hey, Dad will stop you from doing a burnout in the Walmart parking lot.” It’s the adult equivalent of being grounded, but your wallet will thank you.
Also, never let your car insurance lapse—even for a day. That’s like writing “I’m a risky idiot” on your forehead in marker. Insurers will triple your rate, and you’ll end up paying more for insurance than for a used Lamborghini (okay, maybe not, but close).
So, go forth, young speedster, and buy a car that makes insurance companies yawn. Your bank account—and your ability to buy gas—will thank you. And remember: the cheapest car to insure is usually the one your grandparents drive. Embrace the beige. Your future self will high-five you.