
Let’s be honest: keeping up with savings rates can feel like watching paint dry—except the paint keeps changing color. NS&I just launched a new set of Fixed-Rate Bonds, and the headline news is that rates have slipped lower. Before you sigh and scroll away, grab your favorite coffee—because this shift is actually a fascinating little window into where the economy is heading.
The new bonds offer a one-year fix at 3.55% and a three-year fix at 3.70%. Compare that to last year’s highs of over 4%, and it stings a little. But this isn’t a disaster; it’s a recalibration—like your favorite jeans shrinking after one wash. Annoying, but not the end of the world.
Why the drop? Blame the vibes
Think of interest rates like a mood ring for the economy. When inflation started running hot, the Bank of England raised rates faster than a teenager dodging chores. Now, with inflation settling down, the pressure is off. NS&I follows the market, not the other way around. They’re essentially saying, “We don’t need to pay as much to borrow your cash.”
Must Read
Fun fact: NS&I is backed by the UK Treasury, meaning your money is safer than a cuddly blanket. But that safety comes at a price—literally. You’ll almost always earn a bit less than top high-street banks. Think of it as the “peace of mind tax.”
For comparison, the best easy-access accounts now hover around 4.5% to 5%. So locking in at 3.55% for a year feels… underwhelming. However, rates are expected to fall further in 2025, so fixing now might be like buying a ticket for a concert you know will sell out later.
Is there a silver lining? Yes, actually
If you’re the type who loses sleep over market swings, these bonds are Valium for your wallet. The interest is guaranteed, and you can invest from just £500 up to £1 million. It’s boring money, and sometimes boring is brilliant. Like wearing a beige trench coat—not flashy, but it never goes out of style.
Practical tip: Don’t put all your eggs in one basket. Use these bonds for the portion of your savings you need to feel truly untouchable. Keep the rest in a higher-rate easy-access account or a stocks and shares ISA if you’re feeling spicy.
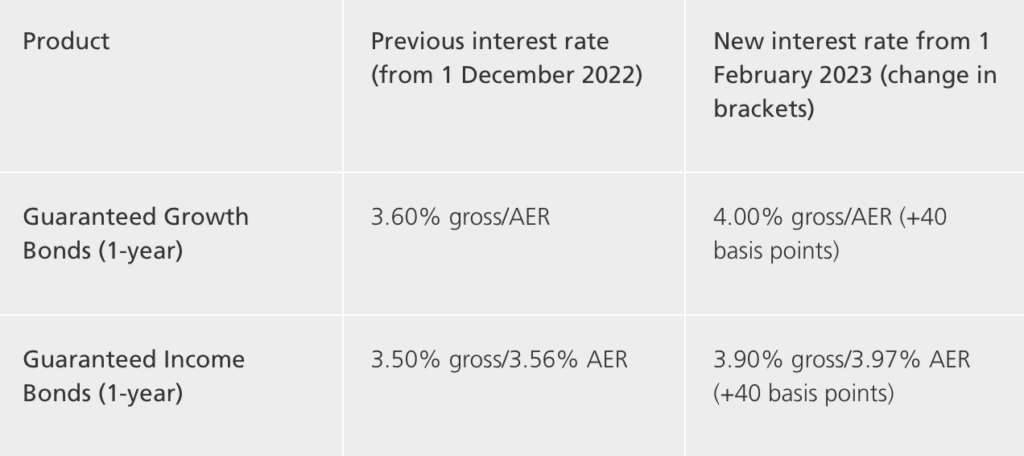 NS&I brings back one-year fixed rate Bonds - Professional Paraplanner
Remember the Friends episode where Monica hides her emergency money in a freezer bag? This is that, but with a better interest rate. Less ice cream, more compound growth.
A cultural crash course in “boring money”
In Japanese culture, there’s a concept called mottainai—a regret over waste. Letting cash rot in a 0% current account is pure mottainai. Even a 3.55% bond is better than nothing, especially if you factor in inflation dropping to around 2%. Your real return might actually be positive. That’s a win in 2025’s world.
Fun fact: The first NS&I savings product was launched in 1861 as the Post Office Savings Bank. You could deposit a single shilling. Queen Victoria was on the throne. If your grandmother had opened an account then, she’d be rolling in interest—though she’d probably be a ghost by now. Point is: NS&I has serious staying power.
Another tip: Check the early withdrawal penalties. If you pull your money out of the three-year bond early, you lose 90 days of interest. That’s like missing three months of Netflix—annoying but survivable. For the one-year bond, it’s just 30 days.
So, should you buy? Let’s game it out
Imagine you’re at a cocktail party. The economy is that slightly tipsy friend who keeps changing his mind. Last year he was shouting about high rates; now he’s whispering about cuts. Fixing now is like saying, “I trust the DJ’s playlist for the next 12 months.” It’s a commitment, but a safe one.
 NS&I slashes the interest rate on its three-year fixed savings bond
If you have cash sitting in a savings account earning less than 3%, moving it to NS&I is a no-brainer—even at these lower rates. You’ll earn more, and you’ll sleep better. Think of it as financial hygiene: like flossing, but for your bank balance.
Practical hack: Use the NS&I calculator on their site. Type in £10,000 and see that 3.55% gives you £355 after a year. Not a Tesla, but a nice weekend in Paris. Or a year’s supply of artisanal cheese. Your call.
A short reflection to bring it home
Here’s the truth: life is full of small, unglamorous decisions. Which brand of toilet paper to buy. Whether to walk or take the bus. Where to park your savings. NS&I’s new lower rates won’t make you feel like a Wall Street wolf. But they might give you the quiet satisfaction of knowing your money is working ever so slightly harder than it was yesterday.
It’s like choosing a cozy night in over a wild party. Not exciting, but your future self will thank you when you wake up rested—and with a little extra cash. Sometimes the best financial move is the one that feels like a shrug. In a world of noise, a calm, boring bond is a small act of rebellion.
So go ahead. Don’t overthink it. Bonds are like bread—just because they’re a little stale today doesn’t mean they won’t make a great sandwich tomorrow. Now, go enjoy that coffee. Your savings can wait.